SINGAPORE, 1 October 2026. The global sustainability debate is entering a new phase.
For much of the past decade, corporate attention has centred on sustainability commitments, ESG disclosures and net zero targets. These remain important. But a harder question is moving to the foreground: how can climate ambition be translated into measurable environmental outcomes, credible economic assets, and capital capable of financing the transition at scale?
That question framed Beyond ESG: Carbon, Capital & the New Sustainability Economy, a forum in Singapore that brought together perspectives spanning diplomacy and public policy, international carbon markets, project development, climate finance and market infrastructure.
RegTech.com was honoured to attend the forum and came away with several takeaways for the region's carbon and climate finance markets.
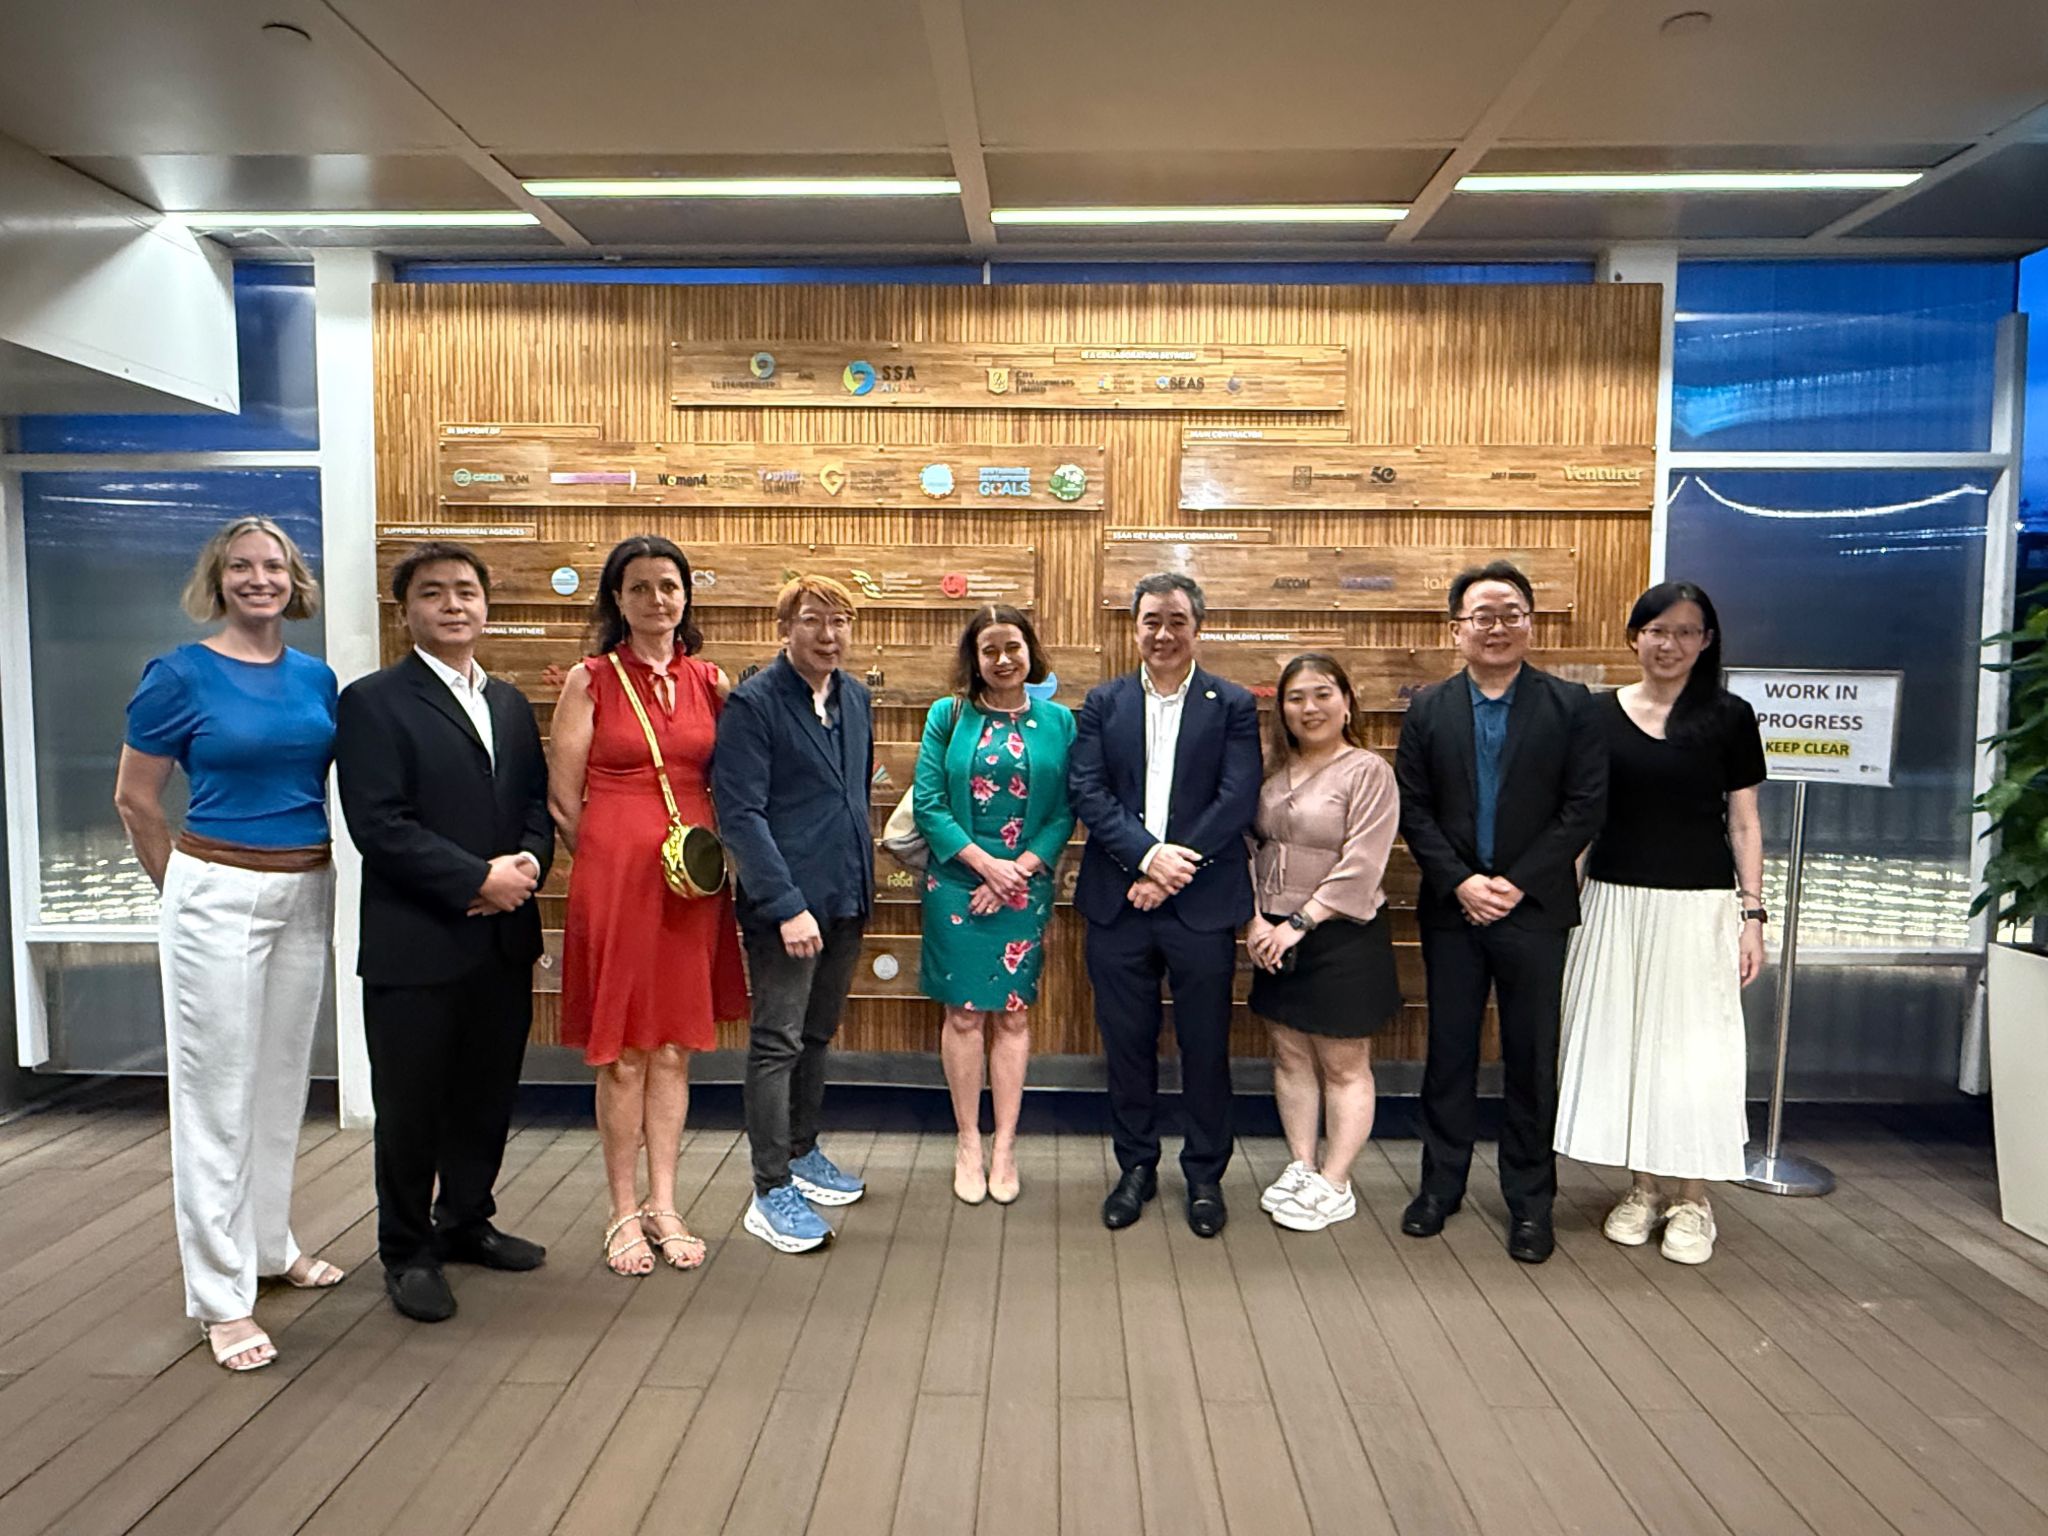
H.E. Robyn Mudie, Australian High Commissioner to Singapore, opened the discussion by placing climate action within the wider realities of geopolitics, energy security and economic development. Björn Fondén, International Policy Manager and APAC Lead at the International Emissions Trading Association (IETA), examined how carbon pricing can change economic incentives. Dr Victor Tay, Group CEO of Global Catalyst Advisory (GCA), moved the discussion from policy to the project level, examining how climate impact can become measurable, credible and bankable. Oi Yee Choo, Chief Executive Officer of Climate Impact X (CIX), completed the value chain by examining how credible carbon assets find buyers, acquire differentiated value and reach increasingly sophisticated markets.
Together, their presentations pointed towards a broader transformation. Carbon markets are moving beyond a conversation centred on offsetting towards one about economic infrastructure, capital allocation and measurable climate outcomes.
Climate action meets economic reality
For High Commissioner Robyn Mudie, the energy transition can no longer be separated from the wider economic and geopolitical environment.
Recent global energy shocks have forced governments to confront energy security, affordability and decarbonisation simultaneously. At the same time, the Australia-Singapore relationship has entered a new phase through the Comprehensive Strategic Partnership 2.0, under which the transition to net zero forms a dedicated pillar of bilateral cooperation.
The implications extend well beyond environmental policy.
Australia's Southeast Asia Economic Strategy to 2040 is seeking deeper economic engagement with the region, including climate-related investment. Robyn noted that more than A$4 billion in new Australian investment had been supported since 2023. She also highlighted the A$2 billion Southeast Asia Investment Financing Facility, including A$177 million invested in Singapore's FAST-P initiative to help unlock private capital for clean energy and sustainable infrastructure across Southeast Asia.
The Australia-Singapore Green Economy Agreement similarly links emerging green supply chains, cross-border electricity trade, sustainable finance and innovation. Robyn characterised its objective as turning climate ambition into economic opportunity by bringing together trade, growth and climate action.
Carbon markets form part of this architecture. Australia, she said, recognises the contribution that high-integrity international carbon markets can make towards global emissions reduction, while supporting Article 6 arrangements that produce “real verifiable climate outcomes”. She also identified a policy dilemma increasingly confronting governments worldwide: how to accelerate decarbonisation while preserving competitiveness, encouraging investment and managing carbon leakage.
It was an appropriate starting point for the forum. Climate change may begin as an environmental challenge, but the mechanisms for addressing it increasingly intersect with economics, trade, technology, competitiveness and capital.
Carbon has a price, and price changes behaviour
IETA's Björn Fondén took the discussion from diplomacy into the economics of carbon.
The fundamental rationale behind carbon pricing is straightforward. Greenhouse gas emissions impose costs that historically have not been fully reflected in the price of economic activity. Carbon pricing seeks to internalise that externality. In doing so, it can create stronger incentives for businesses to reduce emissions and innovate, while directing financial flows towards lower-carbon alternatives.
Yet no single carbon market exists.
Björn described an ecosystem encompassing domestic compliance markets, voluntary carbon markets and international markets operating under Article 6 of the Paris Agreement. Compliance markets represent a substantially larger economic system, while voluntary markets occupy a smaller but important role in financing mitigation and removal activities.
Southeast Asia illustrates the diversity of approaches now emerging. Singapore operates a carbon tax and international credit framework. Indonesia has introduced an emissions trading system. Vietnam is developing its market through a pilot phase, while Malaysia, Thailand and the Philippines are at varying stages of developing carbon pricing or emissions market mechanisms.
Article 6 introduces another important dimension. IETA highlighted more than 110 bilateral agreements or memoranda of understanding associated with Article 6.2 implementation, with Asia playing an increasingly prominent role.
Growth, however, has also brought complexity.
The voluntary carbon market has faced scrutiny over additionality, baselines, permanence and leakage, together with questions surrounding social safeguards and corporate claims. IETA acknowledged that concerns over questionable credits and greenwashing have affected confidence. At the same time, stronger integrity frameworks, greater transparency and clearer standards for the use of credits are emerging as part of the market's response.
Björn's central argument was therefore nuanced. Carbon markets are not a silver bullet. With appropriate safeguards and sound policy design, however, they can provide an effective mechanism for directing finance towards climate mitigation and encouraging action where emissions can be reduced most efficiently.
That raises the next question in the value chain. If governments create the rules and carbon pricing creates the incentive, what exactly is the asset that investors and companies are being asked to finance or purchase?
From climate impact to a credible and bankable asset
Dr Victor Tay of Global Catalyst Advisory addressed this question from the project development and financing perspective.
His starting proposition was that climate impact, carbon credits and bankable assets are not interchangeable concepts.
“Before there is a carbon market, there must first be a climate outcome.”
A renewable energy project, reforestation programme, methane reduction initiative or industrial efficiency intervention may create environmental benefit. But environmental benefit alone does not automatically create a carbon asset.
GCA mapped the journey as a chain. A project must first create a genuine reduction, avoidance or removal of emissions. The baseline and additionality must be established. The outcome must then be quantified and measured, supported by appropriate measurement, reporting and verification, independently verified, traceable and ultimately capable of supporting issuance.
For Victor, this distinction is fundamental.
“A carbon credit is not created by ambition. It is created by evidence.”
Carbon is an unusual economic asset. Unlike a building, machine or physical commodity, a tonne of avoided or removed carbon cannot simply be inspected by the investor purchasing it. Its credibility therefore depends upon the evidence supporting the environmental outcome.
This is where technology is becoming increasingly relevant.
IoT sensors can provide operational evidence. Satellite and remote sensing technologies can independently observe physical changes. Digital MRV can make quantification more scalable and auditable. Data architecture and traceability systems can strengthen provenance and the audit trail.
But Victor cautioned against treating technology as a substitute for integrity.
“Technology does not create integrity by itself. It creates better evidence from which integrity can be assessed.”
Sound methodology, additionality, credible baselines, independent verification and governance remain essential.
That principle leads directly to financing.
“You cannot finance what you cannot prove.”
GCA proposed four interdependent tests for carbon project bankability: the underlying project must be deliverable; the carbon outcome must withstand scrutiny; the economics must remain viable under realistic scenarios; and the risks and projected cash flows must support a financeable capital structure.
This creates an important distinction between generating carbon credits and creating an investment proposition.
“A project can generate carbon credits and still be unbankable. Investors ultimately finance credible cash flows, not climate aspirations.”
A project may qualify technically for carbon credits yet remain difficult to finance because of execution risk, uncertain carbon volumes, issuance timing, weak counterparties, insufficient revenue visibility or an inappropriate capital structure.
This, Victor argued, creates a fundamental financing challenge.
“Carbon credits are generated at the end of the process, but capital is required at the beginning.”
Project developers need capital for land, equipment, implementation, operations, monitoring and verification long before carbon revenues may materialise. Closing that gap may require combinations of sponsor equity, commercial debt, concessional finance, guarantees, long-term offtake arrangements and other risk-sharing mechanisms.
The objective is not to make risk disappear.
“Bankability does not mean eliminating risk. It means identifying it, allocating it, mitigating it and pricing it.”
The wider implication is that climate finance should not be treated as something introduced only after a project has produced credits. Financing considerations need to be integrated much earlier into project design.
As Victor summarised:
“Bankability is engineered, not discovered.”
From credible carbon to market value
CIX Chief Executive Oi Yee Choo then took the discussion from asset creation into the marketplace.
Her presentation posed three deceptively simple questions:
Who wants it? What is it worth? How does it reach the market?
The answers demonstrate why carbon is unlikely to behave as a completely homogeneous commodity.
Demand varies according to purpose. A corporation pursuing voluntary climate action may have different requirements from an entity meeting a carbon tax obligation, an aviation participant complying with sectoral requirements, or a company procuring durable removals as part of a longer term net zero strategy.
Price therefore reflects considerably more than a nominal tonne of carbon dioxide equivalent. CIX identified attributes including eligibility, integrity, durability, delivery certainty, vintage, geography, co-benefits, claims defensibility and scarcity.
The market is consequently becoming more differentiated.
CIX envisaged liquidity developing around distinct use cases, including compliance-eligible credits, quality-filtered voluntary credits and durable removals. Procurement itself is also evolving from occasional offset purchases towards a more structured portfolio discipline encompassing eligibility, quality assessment, sourcing, contracting, settlement, registry transfer, retirement and reporting.
This shift could have significant implications for climate finance.
Longer-dated procurement can provide project developers with greater revenue certainty. Where future demand is sufficiently credible and contractual, it can help convert project quality into financeability, connecting the market directly back to the bankability challenge identified by GCA.
Singapore offers an important regional example. CIX highlighted the interaction between the country's carbon tax, the permitted use of eligible international carbon credits and Article 6 arrangements. Such architecture can create a policy-backed demand channel connecting international mitigation projects with identifiable corporate use cases.
In this sense, policy does not replace markets. It can make demand sufficiently clear for markets to price and execute.
ASEAN's opportunity: connecting the carbon value chain
Taken together, the four perspectives revealed an emerging climate economy.
Governments establish policy credibility and international cooperation. Carbon pricing changes incentives. Project developers translate real-world decarbonisation into measurable outcomes. MRV, verification and traceability create evidence. Financial structures bring capital forward. Market infrastructure connects credible supply with differentiated demand. Price discovery then communicates which attributes buyers value.
For ASEAN, this architecture could be particularly consequential.
The region combines rapidly growing energy demand, substantial natural capital, major industrial and agricultural sectors, evolving carbon policies and significant requirements for transition finance. Yet fragmentation remains a challenge. Different national regulations, methodologies, eligibility criteria and market structures can increase transaction costs precisely when investors require scale, comparability and confidence.
The next phase may therefore depend less on creating additional disconnected carbon initiatives and more on connecting policy, integrity, technology, finance and markets into an interoperable ecosystem.
That was perhaps the strongest message emerging from Beyond ESG.
The future of sustainability will not be defined simply by which organisations make the strongest commitments or produce the most sophisticated disclosures. Nor will carbon markets succeed merely by increasing the number of credits available.
The more consequential test is whether the system can repeatedly transform real climate outcomes into trusted evidence, trusted evidence into bankable assets, and bankable assets into capital for further decarbonisation.
As Victor put it:
“The market may determine the price of carbon. But credibility determines whether there is an asset worth pricing in the first place.”
In that sense, moving beyond ESG does not mean abandoning sustainability reporting. It means extending the journey from disclosure to decarbonisation, from measurement to credibility, and from credibility to capital.
Carbon increasingly has a price.
The next challenge is ensuring that climate impact has credible value.